Start an emergency fund from $0: how much to save, where to keep it and 7 simple steps for US households, with current savings rates and real numbers.
In short: To start an emergency fund, open a separate savings account, set a first goal of $500 to $1,000, and move a small amount into it automatically every payday. Once you reach that starter goal, build toward three to six months of essential expenses in a high-yield savings account. You don’t need a big paycheck to begin. You need a separate account and a habit you don’t have to remember.
Most households don’t have much of a cushion. The Federal Reserve found that 63% of US adults would cover a surprise $400 expense with cash or its equivalent in 2025, the same share as in 2023 and 2024.[1] The rest would need another way to pay, such as borrowing, using a credit card or going without.
This guide shows you how to start an emergency fund from zero, how much to aim for, where to keep the money, and what to do if your budget is already tight.

Table of Contents
- What an emergency fund is (and isn’t)
- Why it matters: what the latest US data shows
- How much should you save?
- 7 steps to start an emergency fund
- A realistic plan from $0
- Where to keep your emergency fund
- How to start an emergency fund when money is tight
- Emergency fund, debt or investing: what comes first?
- Common mistakes
- Frequently asked questions
- Sources
What an Emergency Fund Is (and Isn’t)
An emergency fund is cash set aside only for unexpected, necessary costs. It lives in a safe account you can reach within a day or two, and it is separate from your everyday checking account so you don’t spend it by accident.
What counts as an emergency
- Job loss or a sudden drop in hours
- Urgent medical or dental bills
- A car repair you need to get to work
- A home repair that can’t wait, like a broken furnace or a burst pipe
- Emergency travel for a family crisis
What doesn’t count
Holidays, vacations, sales and annual bills you know are coming, like insurance premiums or car registration, aren’t emergencies. Those are predictable. Plan for them in your regular budget, ideally with a budgeting app or spreadsheet that spreads the cost across the year.
Why It Matters: What the Latest US Data Shows
- The Federal Reserve: 63% of adults would cover a $400 emergency expense using cash or its equivalent in 2025.[1]
- Bankrate: 24% of Americans said they had no emergency savings, and 46% said they had enough to cover three months of expenses (May 2025 survey). In a December 2025 survey, 47% said they could cover a $1,000 emergency expense.[2]
- The job market: In September 2026 the unemployment rate was 4.2%, and about 1.9 million people had been out of work for 27 weeks or more, 27.1% of all unemployed workers.[3]
That last number is why three to six months is a common target. If a job search lasts about half a year, a cushion of that size keeps the rent paid while you look.
What a small cushion saves you
Suppose a $1,200 car repair goes on a credit card at 22% APR, and you pay it off over 12 months. The monthly payment is about $112, and you pay roughly $148 in interest. With a $1,200 cushion, the repair costs $1,200 and nothing more. The money also stays out of your credit utilization, which can affect your score.
How Much Should You Save?
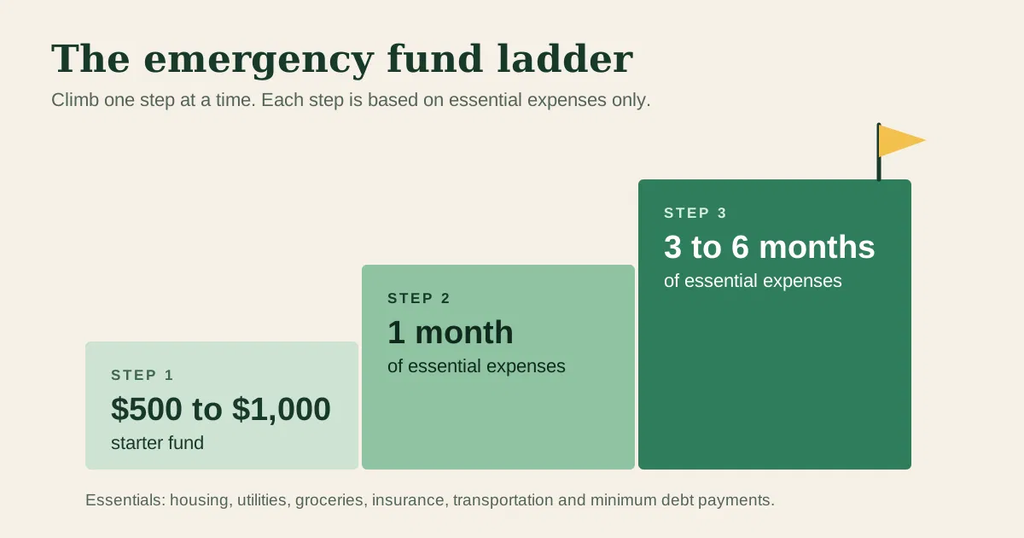
Think of it as a ladder with three steps, based on essential expenses only. Essentials are the bills you must pay even in a bad month: housing, utilities, groceries, insurance, transportation, minimum debt payments and basic phone and internet.

- Starter fund: $500 to $1,000. This covers most small surprises, like a flat tire or a vet bill.
- One month of essentials. A cushion for a short gap in income.
- Three to six months of essentials. A full emergency fund.
| Monthly essentials | 1 month | 3 months | 6 months |
|---|---|---|---|
| $2,500 | $2,500 | $7,500 | $15,000 |
| $3,500 | $3,500 | $10,500 | $21,000 |
| $5,000 | $5,000 | $15,000 | $30,000 |
When to aim for six months or more
- You have one income in the household.
- Your income is irregular, such as freelance or commission work.
- You have dependents or a health condition with ongoing costs.
- Your job is specialized, so a search could take longer.
- You own a home or an older car that may need repairs.
When three months may be enough
Two stable incomes, low fixed costs and strong job security can justify a smaller cushion. These are guidelines, not rules. The right number is the one that lets you sleep at night.
7 Steps to Start an Emergency Fund
Step 1: Find your essential monthly number
Add up your must-pay bills for a typical month. Check three months of bank and card statements so you don’t forget irregular items. This number sets your long-term goal.
Step 2: Set a starter goal of $500 to $1,000
A big target can feel impossible, so start small. When you start an emergency fund with a goal you can reach in a few months, you build momentum and get early protection.
Step 3: Open a separate account
When you start an emergency fund, choose a high-yield savings account at an FDIC-insured bank, ideally at a different bank from your checking account. A little distance makes spending it less tempting. Look for no monthly fees and no minimum balance.
Step 4: Automate the deposit on payday
Set up an automatic transfer for the day your paycheck lands. If it’s automatic, you’re not relying on willpower. Here is how fast a steady weekly amount reaches $1,000:
| Weekly amount | Weeks to reach $1,000 | Saved in one year |
|---|---|---|
| $20 | 50 | $1,040 |
| $25 | 40 | $1,300 |
| $50 | 20 | $2,600 |
| $100 | 10 | $5,200 |
Step 5: Find the money
You can start an emergency fund without a raise. Look for money you aren’t using:
- Cancel subscriptions you haven’t touched in two months.
- Send your next tax refund or work bonus straight to the account.
- Sell things you no longer use.
- Take on a short-term side job and deposit every dollar from it.
- Round up purchases, or move any amount left in checking at the end of each month.
Step 6: Write down your rules
Decide in advance what counts as an emergency, so you aren’t deciding while stressed. A simple test: Is it unexpected, necessary and urgent? If any of the three is a no, find another way to pay for it.
Step 7: Refill it, then grow it
If you use the fund, make refilling it your first money goal. Once you hit your starter goal, raise the target to one month, then three. Each time you get a raise, increase your automatic transfer by a small amount.
A Realistic Plan to Start an Emergency Fund From $0
Here is a hypothetical example, not a real person. A household has $3,500 in essential monthly expenses and no savings. They decide to start an emergency fund in three stages.
- Weeks 1 to 20: Save $50 a week, which reaches the $1,000 starter fund.
- Weeks 21 to 45: Raise the transfer to $100 a week. After 25 more weeks they add $2,500, reaching one month of essentials at $3,500.
- Weeks 46 to about 115: Keep saving $100 a week. Another 70 weeks adds $7,000 and reaches three months of essentials, $10,500, in a little over two years.
Tax refunds, bonuses or a raise would shorten that timeline. A budget setback would lengthen it, and that is fine. The plan works because the transfer is automatic and the next target is always close enough to feel reachable.
Where to Keep Your Emergency Fund
The best place is boring: safe, liquid and earning a decent rate.
High-yield savings account
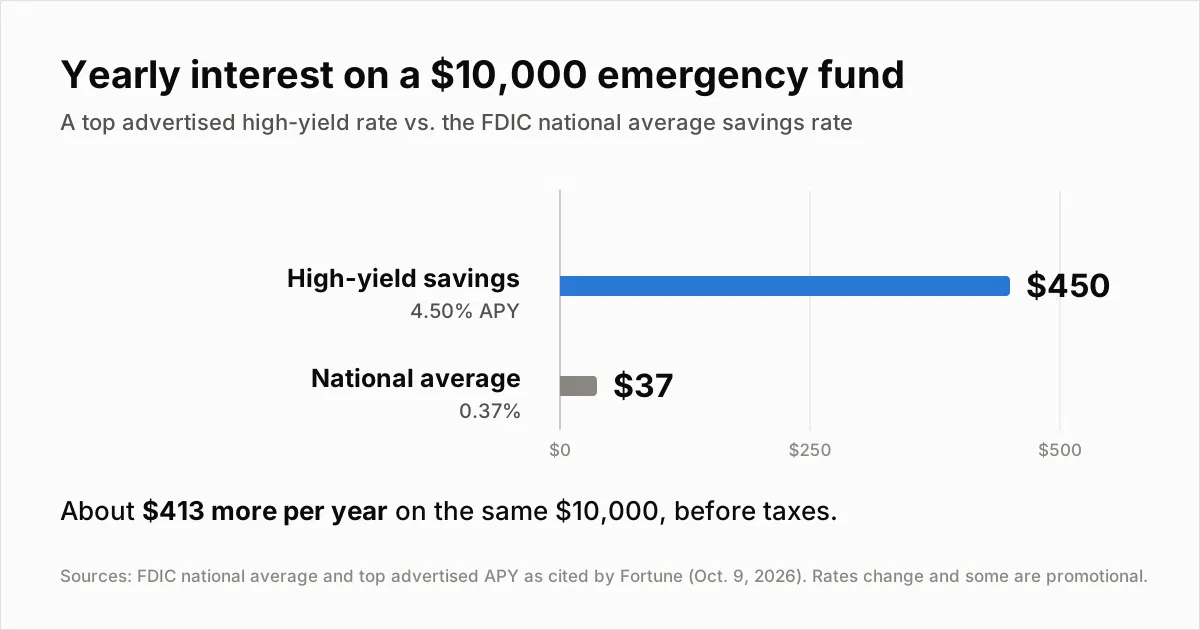
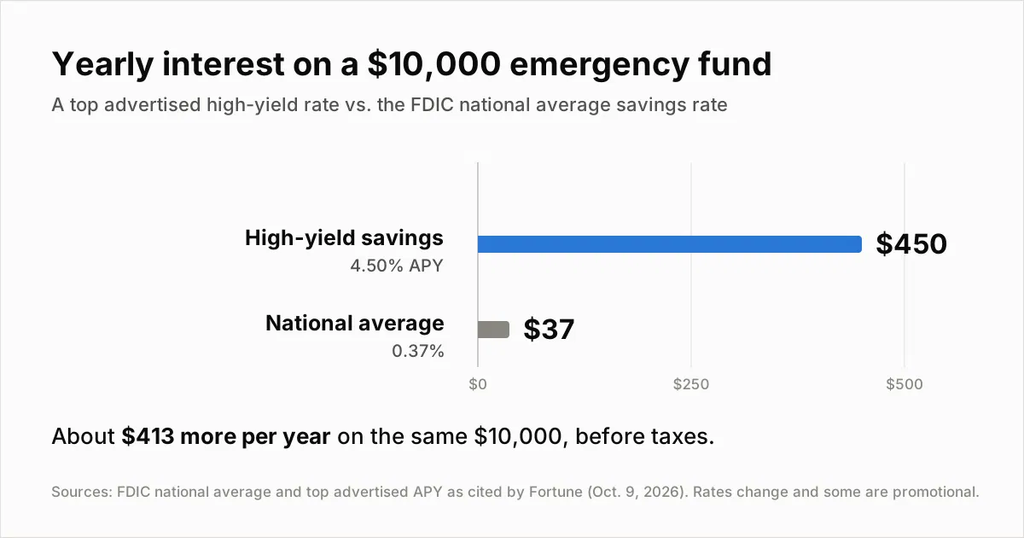
A high-yield savings account is the usual choice. Deposits at an FDIC-insured bank are covered up to $250,000 per depositor, per bank, per ownership category.[5] The FDIC’s national average savings rate was 0.37% in October 2026, while some online accounts advertised up to 4.50% APY.[4]

On $10,000, 4.50% earns about $450 a year, and 0.37% earns about $37. Rates change, and some headline rates are promotional. One advertised 4.20% rate was a 3.30% base rate plus a 0.90-point boost that lasted up to six months.[4] Check the base rate and the terms before you open an account.
Other options
- Money market accounts: Similar to savings accounts, sometimes with check-writing. Confirm the account is insured.
- Credit union savings: Credit unions offer similar federal insurance through the NCUA. Confirm coverage with the institution.
- No-penalty CDs: These can work for the upper rungs of your fund, but make sure you can withdraw without a fee.
What to avoid
Don’t keep your emergency fund in stocks, funds or crypto. The FDIC does not insure investments, and prices can fall right when you need the money.[5] Investing is for goals that are years away. See our beginner investing guide for that part.
How to Start an Emergency Fund When Money Is Tight
If every dollar already has a job, the idea of saving can feel unrealistic. Small steps still count, and you can start an emergency fund with very little. When the CFPB launched its Start Small, Save Up initiative, it said that even small amounts of liquid savings can make a big difference.[6]
Start with $5 or $10
The amount matters less than the habit. A $10 weekly transfer is $520 in a year, and it trains you to save. Raise the amount when you can.
If you have credit card debt
A common approach is to build a small starter fund first, then pay down high-interest debt, then grow the cushion to three months. The starter fund keeps a surprise bill from pushing you back onto the card.
If your income is irregular
Base your target on your lowest-earning months, and save a percentage of every deposit, such as 10%. Aim for the higher end of the range, six months or more.
If you share finances
Decide together how much to save and how to split the contributions. Some couples use a joint account for the fund and separate accounts for personal spending.
Emergency Fund, Debt or Investing: What Comes First?
A common order of operations looks like this:
- Build a starter emergency fund of $500 to $1,000.
- Contribute enough to your employer’s 401(k) to get the full match, if one is offered.
- Pay down high-interest debt.
- Grow your emergency fund to three to six months of essentials.
- Invest more for long-term goals.
Your situation may call for a different order, so adjust it to fit. If a car payment is part of your monthly bills, our car loan guide explains how to keep that payment from squeezing your savings.
Common Mistakes
- Waiting until you have a lot to save. Start now, even if it is small.
- Keeping it in checking. It is easy to spend and earns almost nothing.
- Treating every want as an emergency. Write your rules first.
- Investing it. A market drop can cut your cushion when you need it most.
- Not refilling it. Make rebuilding the fund your first priority after a withdrawal.
- Chasing the top rate. Moving money often for a small rate gain isn’t worth the hassle or the promo traps.
Frequently Asked Questions
How do I start an emergency fund with no money?
Begin with $5 or $10 a week in a separate account and automate it. Add found money, such as a tax refund or a bonus, when it comes. The habit matters more than the amount.
How much should an emergency fund be?
A common target is three to six months of essential expenses, with a starter goal of $500 to $1,000. Aim higher if you have one income, irregular pay or dependents.
Where should I keep my emergency fund?
A high-yield savings account at an FDIC-insured bank is the usual choice. It is safe, easy to reach and pays more than a standard savings account.
Is a high-yield savings account safe?
Deposits at an FDIC-insured bank are covered up to $250,000 per depositor, per bank, per ownership category.[5] Confirm that the bank is FDIC insured before you deposit.
Should I pay off debt or start an emergency fund first?
Many people build a small starter fund first, then pay down high-interest debt, then grow the fund. The starter fund keeps new surprises off your credit card.
Can I invest my emergency fund?
It’s best not to. Investments can lose value and aren’t FDIC insured, so a market drop could shrink your cushion when you need it.
What if I use my emergency fund?
That is what it’s for. Make refilling it your first goal, and restart your automatic transfers as soon as the emergency is over.
Final Thoughts
You don’t need to save six months of expenses this year. Pick a starter amount, open a separate account, and set up a transfer for your next payday. When you start an emergency fund this week, you’ve already done the hardest part, and you can build the rest one step at a time.
Sources
- Federal Reserve: Report on the Economic Well-Being of U.S. Households in 2025 (May 2026)
- Bankrate: Emergency Savings Report (published February 2026)
- U.S. Bureau of Labor Statistics: Employment Situation, September 2026
- Fortune: Best savings account rates (October 9, 2026)
- FDIC: Understanding Deposit Insurance
- CFPB: Start Small, Save Up initiative
Disclaimer: This content is for general educational purposes only and isn’t financial, tax or legal advice. Savings rates change often and may be promotional, so verify current terms with the bank. Examples are illustrations based on the figures cited.