
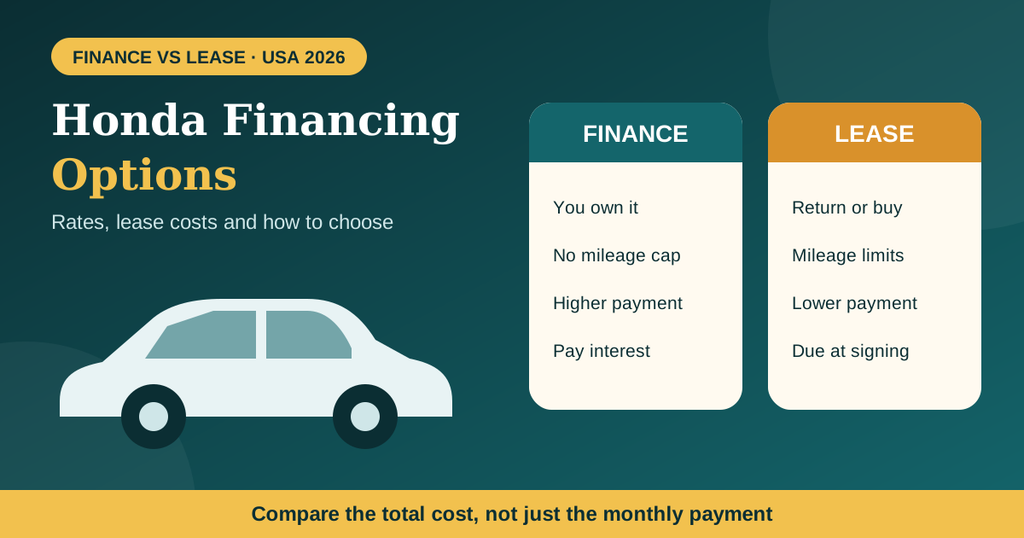
Honda financing options come down to two paths: finance the car and own it, or lease it and give it back. Honda Financial Services offers both, and each one suits a different driver [1]. Which is cheaper depends less on the advertised monthly payment than on the loan term, the amount due at signing, how many miles you drive and how long you plan to keep the car.
This guide covers the main Honda financing options: how each path works, what Honda’s current offers really cost, which credit scores matter, how to apply and the mistakes that cost buyers the most. The numbers come from published sources, and the examples are my own calculations, labeled as such.
Table of Contents
- Honda Financing Options at a Glance
- Financing a Honda: How It Works
- Leasing a Honda: How It Works
- Honda Financing Options Compared: Finance vs Lease
- Current Honda Financing Options and Offers (October 2026)
- What Credit Score Do You Need?
- How to Apply in 6 Steps
- Honda Financing Options Beyond the Dealer
- Add-Ons and Protection Plans
- Mistakes to Avoid
- Final Thoughts
- Frequently Asked Questions
- Sources
Honda Financing Options at a Glance
Honda’s own financing arm lists these Honda financing options on its US site [1]:
- Financing: traditional financing to own the vehicle, with no mileage limits. Honda describes it as the better fit if you keep a car for 5 to 10 years.
- Leasing: less cash up front and lower monthly payments, with mileage limits.
- Honda Loyalty Benefits: available when you return your Honda and lease a new one.
- College Grad Program: $500 off a new vehicle for qualified recent graduates.
- Military Appreciation: $500 off a new Honda for eligible military members, retirees, veterans and their families.
- Protection products: service contracts, maintenance plans and other coverage.
Honda says securing pre-approval is the first step, and its site offers a payment estimator and an online account for managing payments [1]. Program rules and eligibility can change, so confirm the details on Honda’s site or with your dealer.
Financing a Honda: How It Works
When you finance, you borrow the price of the car (minus any down payment) and repay it with interest over a set term. The CFPB puts it simply: you own the vehicle once your payments are done, and each payment goes toward paying down the loan and building equity [3]. You can drive as many miles as you want, though high mileage lowers resale value.
The key trade-off is term length. Honda’s promotional rates are often limited to shorter terms, and longer terms carry higher rates. For example, one listing for the 2027 CR-V shows 3.99% for 24 to 36 months, 4.99% for 37 to 60 months and 5.99% for 61 to 72 months [2].
What the term does to your payment
Here is a $35,000 loan at those three rates. These payments and interest totals are my own calculations using the standard loan formula, as an illustration. They are not a quote.
| Term and rate | Monthly payment | Total interest |
|---|---|---|
| 36 months at 3.99% | $1,033 | $2,195 |
| 60 months at 4.99% | $660 | $4,620 |
| 72 months at 5.99% | $580 | $6,752 |
Stretching from 36 to 72 months cuts the payment by about $453 a month, but adds about $4,557 in interest. A lower payment feels easier, but it is not the same as a cheaper car. For a deeper look at loan terms, see our car loan guide.
Leasing a Honda: How It Works
A lease is a long rental. Your payments cover the car’s depreciation during the lease plus rental charges, and when it ends you return the car [3]. That is why monthly payments are usually lower than a loan payment on the same car.
The trade-offs are real. The CFPB notes that most leases restrict mileage to 10,000 to 15,000 miles a year, that you may be charged for wear and tear at the end, and that ending a lease early can trigger charges it describes as very expensive [3]. At lease end you can return the car and pay any fees, or buy it if your lease includes a purchase option.
The advertised payment is not the full cost
Lease ads lead with a low monthly payment, but most also require an amount due at signing. Spread that amount over the term and the real monthly cost is higher. Using the offers listed by Kelley Blue Book [2], here is the average monthly cost for five sample leases. This is my own calculation and assumes the due-at-signing amount is on top of the payments, so ask the dealer whether it includes your first payment.

| Offer | Advertised payment | Due at signing | Average monthly cost |
|---|---|---|---|
| 2026 Accord LX (36 months) | $209 | $3,999 | $320 |
| 2027 HR-V LX (36 months) | $249 | $3,599 | $349 |
| 2026 Civic Hatchback Sport (39 months) | $249 | $3,999 | $352 |
| 2026 Prologue Touring (36 months) | $279 | $5,099 | $421 |
| 2027 CR-V LX (36 months) | $339 | $4,199 | $456 |
The listing also did not state annual mileage allowances, so ask for that number before you compare any lease [2].
Honda Financing Options Compared: Finance vs Lease
| Question | Finance | Lease |
|---|---|---|
| Who owns the car? | You, once the loan is paid | Honda Financial Services; you return or buy it |
| Monthly payment | Usually higher | Usually lower |
| Cash up front | Down payment, if any | Amount due at signing |
| Mileage | No limit | Limits, commonly 10,000 to 15,000 a year [3] |
| Wear and tear | Affects resale value only | Can trigger end-of-lease charges |
| Leaving early | Sell or trade the car | Can be very expensive [3] |
Financing usually fits you if you drive a lot, keep cars for many years, want to customize the car or want to be payment-free someday.
Leasing usually fits you if you drive moderate miles, like a newer car every few years and want a lower payment. It works best when you can handle the due-at-signing amount and are comfortable with the rules.
If you cannot decide, price both for the same car and compare the total cash you would spend over the first three years, then think about what you would own at the end. A lease leaves you with no car unless you buy it, while a loan leaves you with a car that still has value.
Current Honda Financing Options and Offers (October 2026)
Kelley Blue Book lists these Honda offers, all expiring November 2, 2026 [2]. Each one is limited to well-qualified buyers or lessees, and the page says not all buyers will qualify.
| Model | APR (term) | Lease (term) | Due at signing |
|---|---|---|---|
| 2026 Accord 1.5T LX | Not listed | $209 (36 mo.) | $3,999 |
| 2026 Accord Hybrid Sport | 3.99% (24-60 mo.) | $289 (36 mo.) | $3,999 |
| 2026 Civic Hatchback Sport | Not listed | $249 (39 mo.) | $3,999 |
| 2026 CR-V LX 2WD | 2.99% (24-36 mo.) | $269 (39 mo.) | $4,199 |
| 2027 CR-V LX 2WD | 3.99% (24-36 mo.) | $339 (36 mo.) | $4,199 |
| 2027 HR-V LX 2WD | 3.99% (24-48 mo.) | $249 (36 mo.) | $3,599 |
| 2026 Pilot 2WD EX-L | 3.99% (24-36 mo.) | $409 (36 mo.) | $4,999 |
| 2026 Prologue AWD Touring | 0.99% (24-60 mo.) | $279 (36 mo.) | $5,099 |
| 2026 Ridgeline AWD RTL | 1.99% (24-36 mo.) | $379 (36 mo.) | $4,299 |
Read the fine print. The listing says the offers may not reflect all current deals, availability varies by location, and prices exclude taxes, licensing, tags and dealer fees [2]. Special rates and lease deals also tend to apply to specific trims and terms, so the car you want may not qualify.
Promotional rates are tied to certain trims and short terms. Ask the dealer which rate applies to the exact car and term you want, and ask whether a cash rebate is available instead of the low rate. Sometimes taking the rebate and financing elsewhere costs less, so run the numbers both ways.
What Credit Score Do You Need?
Honda Financial Services does not publish a minimum credit score for any of its financing options. It encourages applicants to check their likely eligibility through pre-approval [5]. The promotional rates above are reserved for well-qualified buyers, which generally means strong credit.
To see how much credit matters, here are the average new-car loan rates by credit tier across all lenders, from Experian’s Q2 2026 data (VantageScore 4.0) [4]:
| Tier | Score range | Average new-car APR |
|---|---|---|
| Super prime | 781 and above | 4.41% |
| Prime | 661 to 780 | 6.15% |
| Near prime | 601 to 660 | 9.71% |
| Subprime | 501 to 600 | 13.52% |
| Deep subprime | 300 to 500 | 16.11% |
These are market averages, not Honda rates. Your own rate depends on the lender, term, vehicle, down payment, income and debts. If your score is near a tier boundary, a few months of paying down card balances and avoiding new credit applications could move you into a cheaper tier.
How to Apply in 6 Steps
Step 1: Set a monthly budget
Decide what payment fits your budget before you compare Honda financing options at a showroom. If you need a tool to track it, see our guide to the best budgeting apps.
Step 2: Check your credit
Review your credit reports for errors and know your score range. It tells you whether the advertised promotions are realistic for you.
Step 3: Get pre-approved
Honda calls pre-approval the first step, and you can also get one from your bank or credit union [1][5]. A pre-approval gives you a rate to compare against the dealer’s Honda financing options.
Step 4: Gather your information
Have your Social Security number, bank account details, employment information, details of the vehicle and your down payment amount ready [5]. Lenders also commonly ask for a driver’s license and proof of income and residence, so bring recent pay stubs.
Step 5: Negotiate the price first
Agree on the vehicle price before you discuss financing or a lease. Then compare Honda financing options by asking for the monthly payment, the APR or money factor, the term, the amount due at signing and the total cost, in writing.
Step 6: Compare and read before you sign
Compare the dealer’s offer with your pre-approval and confirm the contract matches what you were quoted. For a lease, check the mileage limit, the wear-and-tear rules and the early-termination terms.
Honda Financing Options Beyond the Dealer
You are not required to use Honda Financial Services. You will likely find competitive rates through Honda’s financing arm or a financial institution, and credit unions are often worth checking [5]. Credit union rates are currently capped at 18%, and you generally need to be a member [5].
The simplest approach is to get one outside pre-approval and let the dealer try to beat it. Manufacturer promotional rates can sometimes be hard for banks to match on new cars, so the dealer may win. If the dealer cannot beat your pre-approval, you have a good rate already in hand.
Also check whether you qualify for the Honda College Grad or Military Appreciation programs, which are each worth $500 on a new vehicle [1]. Ask whether they can be combined with a specific offer, since that is up to the program rules.
Add-Ons and Protection Plans
Honda’s financing page lists service contracts, maintenance plans and other protection products [1]. They can make sense for some drivers, but they raise the amount you finance and the interest you pay on it.
Before you agree to any add-on, ask for its price in writing, what it covers, how long it lasts and whether it is optional. Then ask how much it adds to your monthly payment. A plan that looks cheap per month can be expensive over a 72-month loan.
Mistakes to Avoid
These are the most common mistakes when comparing Honda financing options:
- Shopping by monthly payment alone. Compare total cost, including interest, fees and the amount due at signing.
- Stretching the term to hit a payment. As the table above shows, a longer loan can add thousands in interest.
- Rolling in negative equity. Edmunds reported that 29.6% of new-vehicle trade-ins in Q2 2026 had negative equity, averaging $6,884 owed beyond the car’s value [6]. Adding that to a new loan raises your payment and your risk.
- Ignoring lease limits. Mileage and wear-and-tear charges can erase the savings of a low payment [3].
- Assuming the ad applies to you. The headline rate is for well-qualified buyers, and your offer may differ [2].
- Skipping outside quotes. One pre-approval from a bank or credit union costs little and gives you leverage.
Final Thoughts
The best of the Honda financing options is the one with the lowest total cost for how you actually drive. If you keep cars for years and drive a lot, financing usually fits better. If you want a lower payment and a newer car every few years, a lease can work, as long as you accept the limits.
Before you visit a dealer, set your budget, check your credit and get one outside pre-approval. Then compare every offer by its total cost, not its headline number. Offers on this page expire November 2, 2026, so confirm current terms with your dealer.
Frequently Asked Questions
What are the Honda financing options?
Honda Financial Services offers traditional financing to own the car and leasing to return it. It also lists a loyalty benefit for lessees who lease again, a $500 college grad program, a $500 military program and protection products [1].
Is it better to lease or finance a Honda?
Leasing usually means a lower payment and mileage limits. Financing means a higher payment and ownership with no mileage cap. Honda suggests financing for drivers who keep a car for 5 to 10 years [1].
What credit score do I need to finance a Honda?
Honda Financial Services does not disclose a minimum credit score. Promotional offers are for well-qualified buyers, and pre-approval shows your likely eligibility [2][5].
Does Honda offer 0% financing?
Honda financing options change often. In the October 2026 listing, the lowest advertised rate was 0.99% on the 2026 Prologue AWD Touring for well-qualified buyers, and the offer expires November 2, 2026 [2]. Confirm current rates with a dealer.
What happens at the end of a Honda lease?
In general you can return the car and pay any end-of-lease fees, or buy it if your lease includes a purchase option [3]. Honda lists lease-end information and a loyalty benefit for returning and leasing again [1].
Can I finance a Honda through my bank or credit union?
Yes. You are not required to use Honda Financial Services, and an outside pre-approval gives you a rate to compare [5].
Sources
- Honda Financial Services: Financing Your Honda (US).
- Kelley Blue Book: Best Honda Deals, Incentives and Rebates for October 2026 (offers expire Nov. 2, 2026).
- Consumer Financial Protection Bureau: What should I know about leasing versus buying a car?
- Experian: Average Car Loan Interest Rates by Credit Score (Q2 2026 averages).
- LendingTree: Honda Financing: What To Know in 2026.
- Edmunds: Q2 2026 negative equity report.
This article is general information, not financial advice, and it is not affiliated with or endorsed by Honda. Rates, offers and program rules change and vary by location, credit and vehicle. Confirm all terms with Honda Financial Services or your dealer before you sign.